Tampa Bay Area Real Estate News & Market Trends

You'll discover my blog to be a rich source of information that covers an array of topics, from local market statistics and home values to community events. The reason for this is that I hold a deep passion for the community, and my ultimate goal is to assist you in finding your ideal place within it.

If you have any questions, please don't hesitate to contact me. I'm always eager to engage in conversation with you!

Oct. 22, 2026

Tampa Bay's September 2026 Housing Numbers: Prices, Sales and a Surprising Split

Tampa Bay's September 2026 Housing Numbers: Prices, Sales and a Surprising Split illustration

The latest September housing numbers tell an interesting story: fewer sales, relatively steady closed-sale prices, and plenty of sellers adjusting their asking prices. If that sounds contradictory, welcome to real estate. Different numbers measure different things, and they do not always move in the same direction.

View More
Oct. 22, 2026

Tampa Bay Buyers Are Gaining Leverage, but Mortgage Rates Complicate the Math

Tampa Bay Buyers Are Gaining Leverage, but Mortgage Rates Complicate the Math illustrationHere's a sentence we haven't been hearing much in recent years: the Tampa-St. Petersburg-Clearwater area has been classified as a buyer's market. That does not mean every seller is desperate or every home is a bargain. It does mean the balance between buyers and sellers has changed, and a report released this week gives us some numbers to work with.

View More
Oct. 22, 2026

Sunrise Hills Breaks Ground in Brooksville: 4,000 Homes, a Lagoon and Much More

Sunrise Hills Breaks Ground in Brooksville: 4,000 Homes, a Lagoon and Much More illustrationBrooksville is getting another very large master-planned community, and this one has moved beyond the proposal stage. Metro Development Group broke ground on Sunrise Hills on October 14, according to the Tampa Bay Business Journal. The plan covers about 1,100 acres along Cortez Boulevard, near Sherman Hills Golf Course and the Withlacoochee State Trail.

View More
Oct. 22, 2026

Two 44-Story Condo Towers Proposed for the Hilton Bayfront Site in St. Pete

Two 44-Story Condo Towers Proposed for the Hilton Bayfront Site in St. Pete illustrationThe skyline of downtown St. Petersburg may be getting another dramatic addition. Developer Kolter Urban has proposed replacing the Hilton St. Petersburg Bayfront with not one but two 44-story condominium towers. If the plan moves forward, this would be one of the city's biggest residential redevelopment projects.

View More
Oct. 22, 2026

A $100 Million Surf Park Is Planned for Two Rivers in Zephyrhills

A $100 Million Surf Park Is Planned for Two Rivers in Zephyrhills illustration

A surf park in Zephyrhills? That sounds a little strange until you see what is being planned at Two Rivers. Peak Surf Park is a proposed 35-acre destination with an artificial wave lagoon, a half-mile sandy beach and a project budget reported at more than $100 million. This is not another lagoon where you float around on a tube. The main attraction is supposed to be actual surfing.

View More
Posted in Two Rivers, Zephyrhills
Oct. 19, 2026

Pasco County Housing Market Update: October 12–18, 2026

Pasco County Housing Market Update: October 12–18, 2026

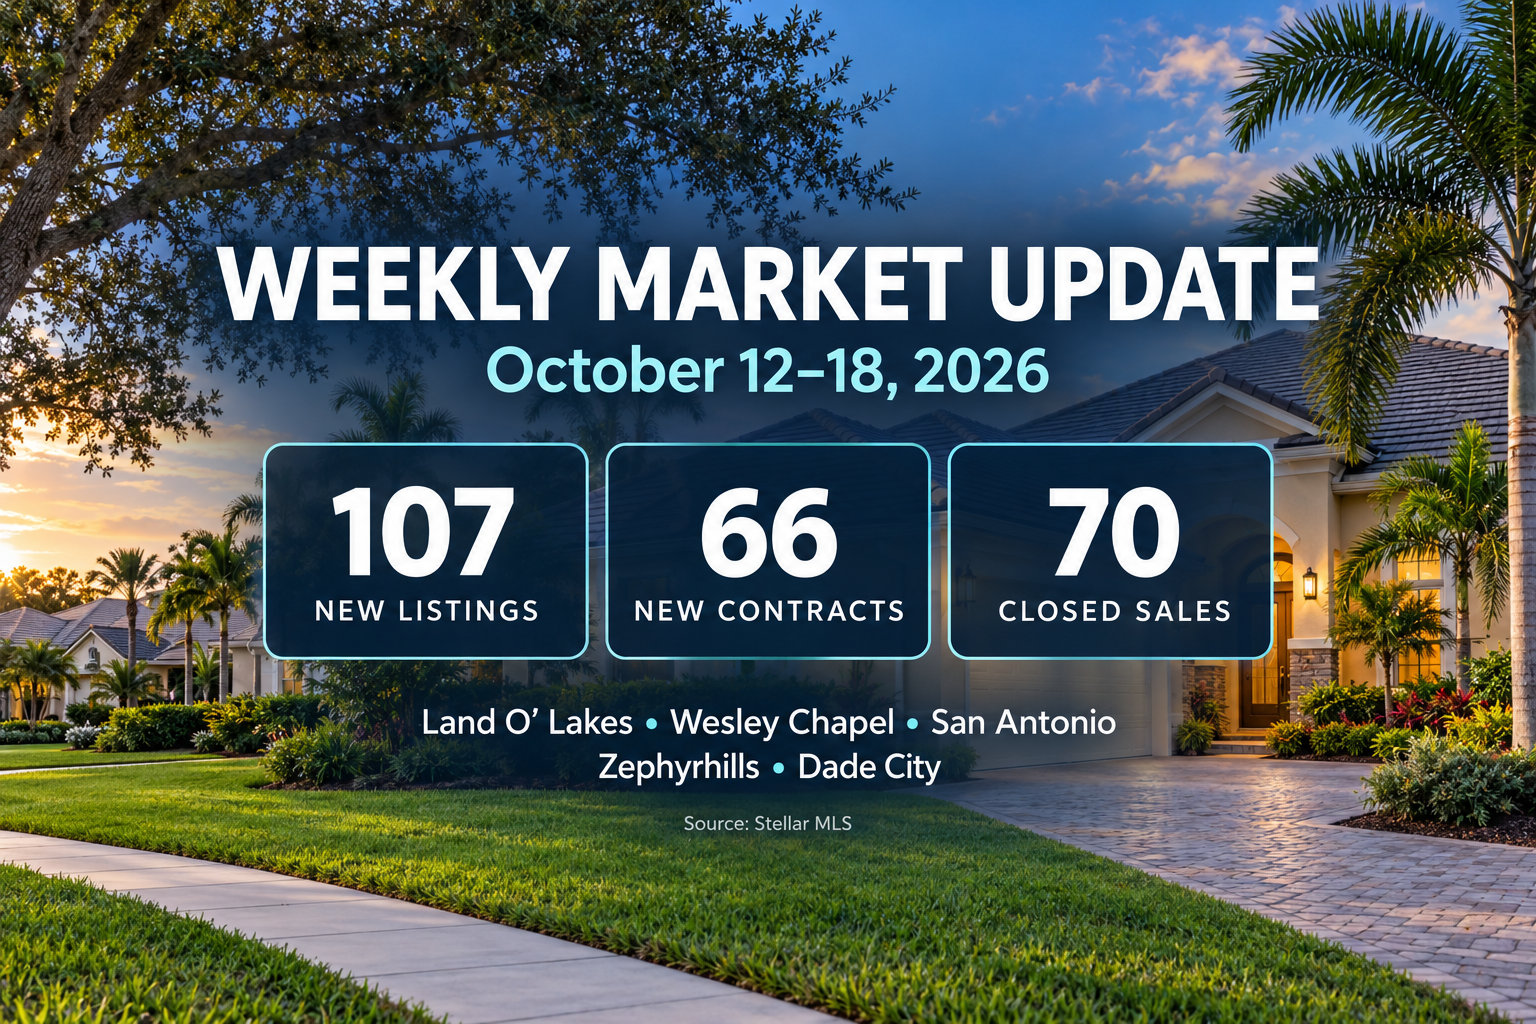
This is the first post in my weekly Monday market update covering Land O’ Lakes, Wesley Chapel, San Antonio, Zephyrhills, and Dade City in Pasco County, Florida. Each week, I’ll share the latest numbers from Stellar MLS and highlight anything worth watching. This week gives us a starting point. As we add more data, we’ll compare activity from week to week and track trends in listings, sales, pricing, and how quickly homes go under contract.This week’s update covers single-family homes across five local markets. From October 12–18, there were 107 new listings, 66 homes going under contract, and 70 closed sales. As of October 19, buyers had 1,629 active listings to choose from across these areas.

One number worth watching: 378 price reductions were reported during the week. Sellers are adjusting asking prices, although we’ll need more weeks of data to see whether that activity is increasing or slowing down.

The Weekly Numbers

MetricAll five areas combined
New listings107
New pending sales66
Closed sales70
Reported price reductions378
Active listings (as of October 19)1,629
Median sale price$419,250
Median days to contract for homes that closed65

New listings outnumbered new contracts by 41. That’s useful to watch, but it doesn’t mean inventory increased by exactly 41 homes. Properties can also leave or return to the market for other reasons. Next week’s active listing count will give us a direct comparison.

What Sold in Each Area?

AreaClosed salesMedian sale priceMedian days to contract
Land O’ Lakes12$482,79568.5
Wesley Chapel29$487,50061
San Antonio4$268,500214
Zephyrhills15$349,00083
Dade City10$375,04546.5

Wesley Chapel accounted for the most closings, with 29 sales. It also had the highest median sale price this week, just above Land O’ Lakes.

Dade City had the shortest median time to contract among the homes that closed, at 46.5 days. San Antonio’s 214-day figure comes from only three sales with timing data, so I wouldn’t draw a broad conclusion from that number alone.

These figures describe the particular homes that sold during the week. The mix of homes sold can move the median price without showing a comparable change in individual home values.

What This Means for Buyers

With 1,629 active listings across the five areas, there are options to compare. The price reductions also make it worth reviewing a home’s price history and time on the market when deciding what to offer.

A reduction alone doesn’t tell us whether a home is a good deal. Recent comparable sales, condition, location, and the current asking price still matter.

What This Means for Sellers

Pricing deserves attention from the start. Buyers can compare your home with other available properties, including listings that have recently lowered their prices.

If your home isn’t getting showings or offers, review the competing listings and recent sales before deciding what to adjust. These regional numbers provide context, but the closest comparable homes will be more useful for setting your price.

This is the first report in my Monday market series. Future updates will compare the weekly numbers so we can track what’s changing in each area.

Thinking about buying or selling in one of these areas? What would you like to know about the market in your neighborhood?

Source: Stellar MLS. Single-family homes in the five selected MLS city areas. Weekly activity covers October 12–18, 2026; active inventory is a snapshot as of October 19. Days-to-contract figures describe homes that closed during the week. Three sales were missing days-to-contract information and were excluded from that calculation. All 70 sales were included in the median sale price. MLS data may be updated after reporting.

Posted in data
Oct. 15, 2026

Pendry Tampa Reaches a Milestone: Questions to Ask Before Buying a New Condo

Pendry Tampa Reaches a Milestone: Questions to Ask Before Buying a New Condo

Axios reported October 13 that Pendry Tampa had completed vertical construction. These are going to be luxury condos set above the Pendry Hotel on Tampa’s Riverwalk featuring amazing amenities with a stellar location.

If you are considering a new condo anywhere, construction updates are worth following. I would also use them as a reminder to ask questions about the purchase itself. Before committing, you want to understand the contract, the expected timing, and what owning the unit would involve.

Here is the general checklist I would bring to a new condo purchase. These are questions to investigate for any development you are considering, rather than findings about this particular project.

Get clear about the expected delivery

Ask what the current completion and closing estimates are, what work remains, and how buyers receive updates. Review the contract’s timing provisions with an appropriate professional, including what happens if dates change. Do not build a moving plan around an informal estimate without understanding the written agreement.

If you need to sell another property first, think through how you would coordinate the two transactions. Would you need temporary housing? Where would your belongings go? What would it cost if the gap lasts longer than you hoped? Those are useful questions to answer before you have a moving company booked.

I would also ask your lender how financing timelines fit the proposed delivery. If you received an early qualification or quote, find out what needs to be updated as closing approaches. Keep the lender informed as the developer’s schedule changes.

Review the full ownership budget

Ask for the current estimated association budget and a clear explanation of what is included in the quoted charges. Find out which expenses you would pay separately and which figures are estimates that may change. I would want those answers in writing before comparing the property with another option.

Put the mortgage payment, estimated taxes, insurance, association charges, parking costs, and any other identified fees on one worksheet. If the development offers optional services, ask how those are priced and whether participation is required. The objective is to understand your own likely expenses.

I would also ask what documents are available concerning maintenance responsibilities and future funding needs. Have a qualified professional help review material you do not understand. A purchase of this size deserves enough time to work through the details.

Check how the property would work for daily life

A floor plan can look great and still leave practical questions unanswered. Ask about storage, deliveries, guest access, elevators, pets, parking assignments, and charging options if you need them. Get the rules that apply to the unit you are considering.

If amenities influence your decision, confirm which are included, which are shared, and when they are expected to be available. Visit the surrounding area at different times if possible. Try the drive you would normally make, and check the places you expect to use regularly.

Compare it with other homes you would actually buy

I would compare the development with other properties that fit your budget and lifestyle, including available resale units. Think about the space you need, the ownership costs you can comfortably handle, and whether you prefer something available sooner.

A downtown condo and a single-family home in Pasco County can meet very different needs. One does not establish the value of the other. Keep the comparison focused on the options that work for your move, then decide which tradeoffs you are comfortable making.

Construction news can be interesting without telling you everything you need to know as a buyer. Ask for the documents, check the budget, and make sure the purchase fits your plans. What would matter most to you when comparing a new condo with an existing home?

Posted in New Construction, Tampa
Oct. 15, 2026

Mortgage Rates at 7.40%: What Tampa Bay Buyers Should Compare Before Making an Offer

Mortgage Rates at 7.40%: What Tampa Bay Buyers Should Compare Before Making an Offer

If you are looking at homes around Tampa Bay, it is worth updating your payment estimate before you update your saved listings. The price range that felt comfortable a few weeks ago may need another look when your available mortgage rate changes.

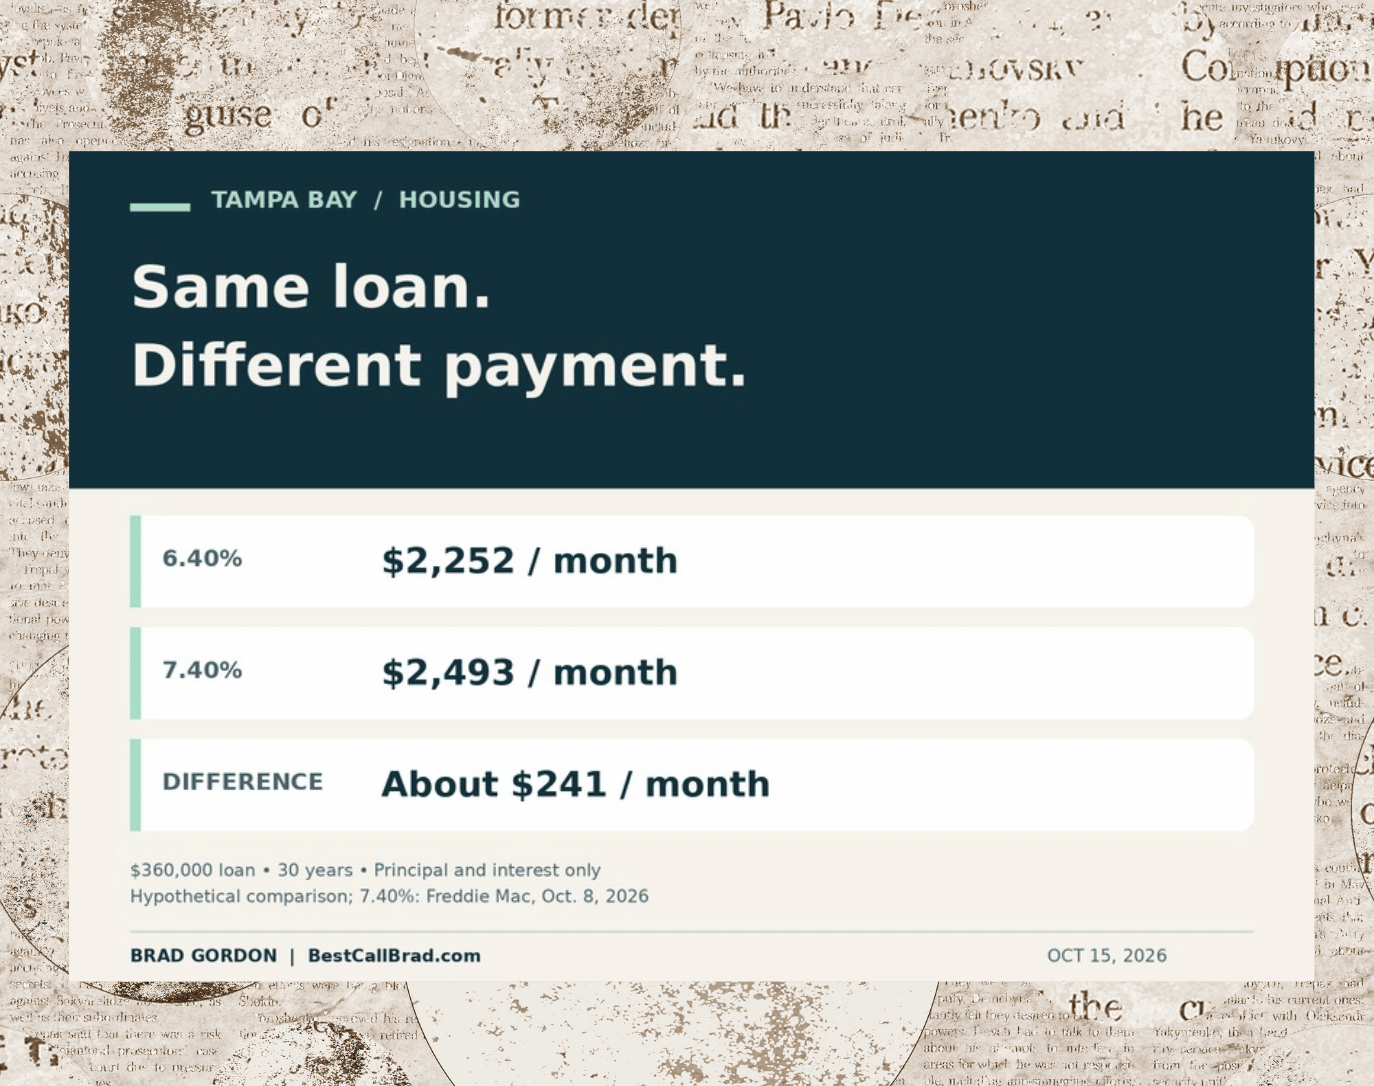
Freddie Mac’s October 8 survey put the national average for a 30-year fixed mortgage at 7.40%, up from 7.28% the previous week. That was the latest survey available when this post was prepared the morning of October 15. It is a national benchmark, rather than a quote for a particular buyer or a Tampa Bay lending average.

Look at what the rate does to your payment

Here is a hypothetical example. On a $360,000 mortgage with a 30-year term, principal and interest would be approximately $2,493 per month at 7.40%. At an illustrative 6.40%, the same calculation comes to about $2,252. That is roughly $241 a month in difference. The 6.40% figure is for comparison only, not an available offer.

Those calculations exclude property taxes, insurance, mortgage insurance, association charges, and other expenses. They show why I would start with an updated lender estimate before deciding whether a home fits. A purchase price by itself does not tell you enough about the payment.

Compare loan quotes using the same assumptions

If you ask multiple lenders for quotes, give them the same purchase price, down payment, and loan type. Ask about the rate, lender fees, points, available credits, and rate-lock terms. You want to understand what you would pay to receive each offer.

The Consumer Financial Protection Bureau explains that discount points are upfront fees paid for a lower interest rate. It also notes that the rate reduction associated with points varies. So a lower advertised rate deserves a closer look at the cost required to get it.

I would ask for the comparison in writing. A lower rate with a higher upfront cost may work for one buyer and be a poor fit for another. Put the monthly payment beside the cash needed to close before deciding which offer deserves more attention.

Run the numbers before paying for a lower rate

Ask your lender to show an option with points and an option without them. Then compare the additional upfront cost with the expected monthly savings. As a simple hypothetical example, paying $4,000 to save $100 per month takes 40 months to recover that cost through payment savings alone.

That basic comparison leaves out factors such as the value of keeping your cash available and what happens if you sell or refinance. It is still a useful question to start with. I would want to understand the tradeoff before agreeing to spend more at closing.

Make the purchase work with the loan you can get now

I would not buy a home that only becomes affordable if you can refinance later. Nobody can promise the timing, cost, or availability of a future loan. Ask yourself whether you would still be comfortable if you needed to keep the original financing longer than expected.

If the current payment is too high, there are practical things to review: the purchase budget, the down payment, other properties, or the timing of the move. You do not have to make a purchase just because you have started looking.

For buyers considering Wesley Chapel, Zephyrhills, or elsewhere around Tampa Bay, I would rather narrow the search around a payment that works than spend weekends touring homes outside a comfortable budget. What monthly payment would let you buy without feeling stretched?

A Special Note To You:

Please know that I am not a lender and am only offering this as advice. Please consult your preferred lender to go over specifics of your situation and how it will impact your decisions.

Posted in Buyer Tips, Lenders
Oct. 15, 2026

Buying in Tampa Bay? Check the Property Tax Estimate Before You Set Your Budget

Buying in Tampa Bay? Check the Property Tax Estimate Before You Set Your Budget

Axios reported October 6 that unchanged or lower Tampa Bay tax rates can still leave homeowners with larger bills.

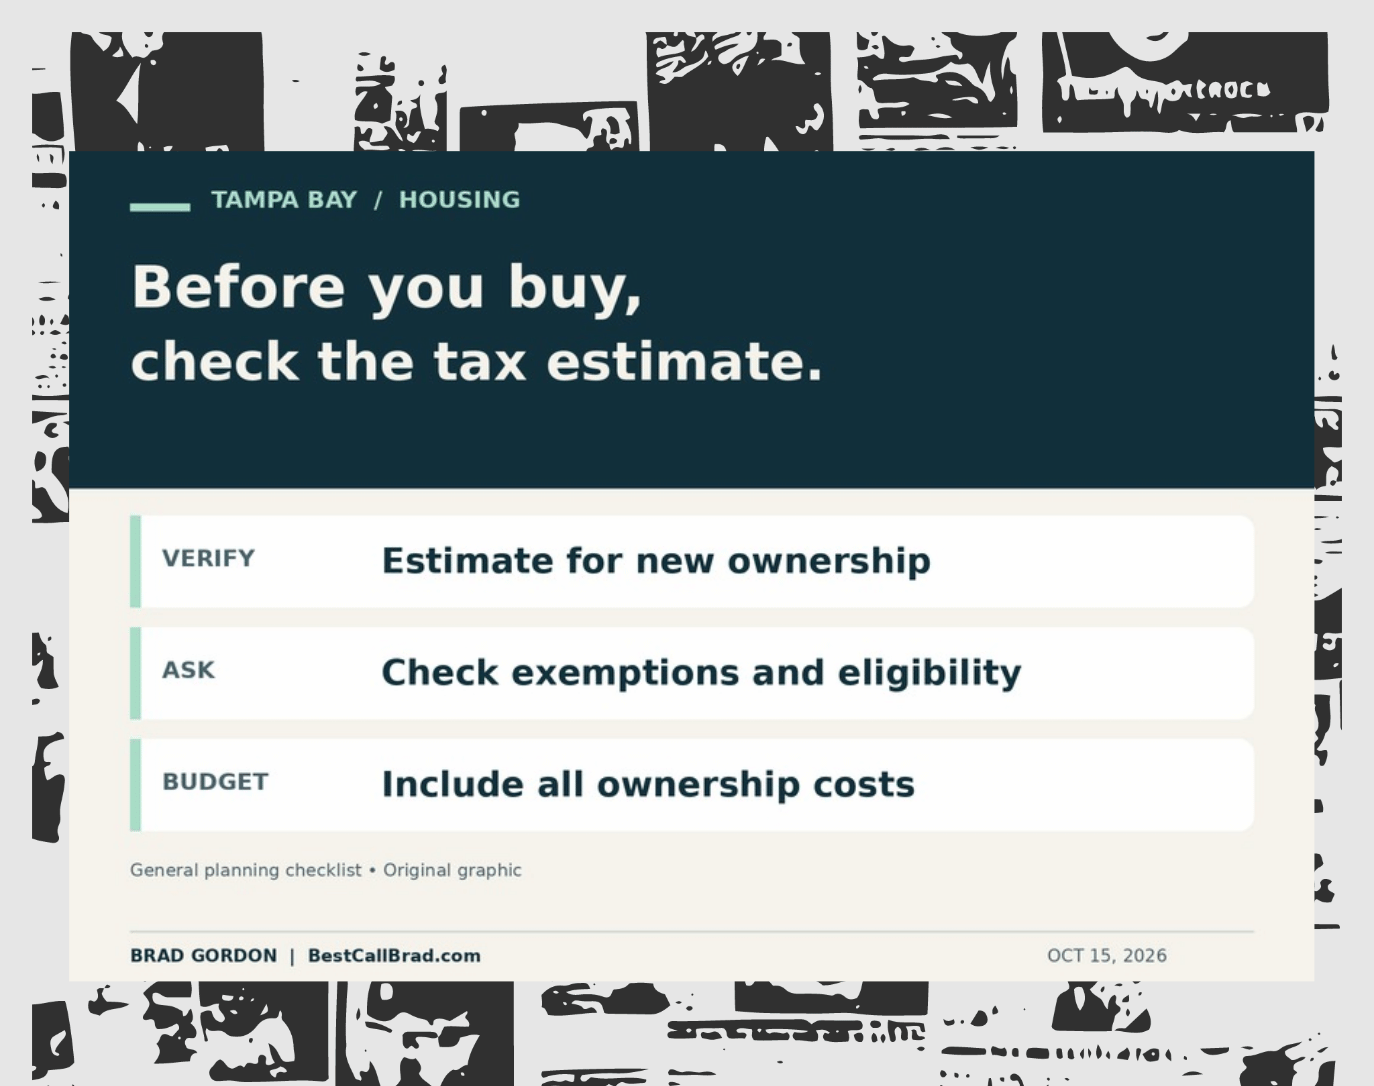
If you are buying, that is a good reason to look closely at the tax number in your estimated monthly payment. I would want to know where that number came from before using it to decide what I can afford.

The Pinellas County Property Appraiser specifically directs buyers to its tax estimator to estimate taxes under new ownership after the first January 1 they own the property. It is a useful starting point when reviewing a home in that county. For a home elsewhere in Tampa Bay, use the appropriate county property appraiser and ask questions about that specific parcel.

Ask whether the estimate uses your purchase situation

When you receive a payment estimate, ask whether the property tax amount comes from the seller’s current bill or an estimate for your ownership. If the answer is unclear, get it clarified before treating that payment as your working budget.

A listing’s tax history is helpful information about the property. I would still want a separate estimate based on the proposed purchase and any exemptions you may qualify for. Do not assume the amount displayed on a search website is the amount you will pay.

Keep a copy of the estimate and note the assumptions used. If the purchase price changes during negotiation, ask whether the estimate needs to be updated. That is easier than trying to remember which numbers were included in an early conversation.

Get exemption questions answered for your circumstances

If you plan to use the property as your primary residence, ask the county property appraiser about homestead eligibility, application requirements, and timing. If you already own a Florida home, ask whether portability could apply to your move. Get those answers for your situation rather than assuming someone else’s experience will match yours.

I would also ask what happens if an exemption is not reflected in the initial estimate. You want a budget that you can work with while the details are being confirmed. Buying should not depend on a benefit that nobody has verified you can receive.

These are good questions to bring up early, especially when you are moving from another state. Put them on the same list as your financing and insurance questions so they are handled before the last few days of the purchase.

Compare homes using a consistent monthly worksheet

For each home you seriously consider, write down principal and interest, estimated property taxes, insurance, and any association or community charges. Ask about assessments and any other property-specific expenses that should be included. Keep recurring costs separate from one-time closing expenses so you can see both clearly.

If one estimate is based on verified information and another uses a rough online number, you are not making a useful comparison yet. Mark the uncertain items and follow up. That small amount of organization can make choosing between two homes much easier.

Leave yourself some room

I would not set a purchase budget that requires every estimate to turn out perfectly. Decide what payment feels comfortable, what cash you want to keep available, and how you would handle an unexpected expense after moving.

Before writing an offer, review the tax estimate with the other ownership costs and ask your lender how those figures are being handled. The point is to make a decision using numbers that fit your purchase. What part of the monthly cost would you want to understand better before buying your next home?

Posted in Buyer Tips
Oct. 15, 2026

A Tampa Bay Price Reduction Is Worth a Look. Here Is What to Check Next

A Tampa Bay Price Reduction Is Worth a Look. Here Is What to Check Next

A price reduction can get your attention fast when you are shopping for a home. If a property you liked is suddenly within your budget, it is absolutely worth taking another look. Just do a little more checking before deciding you found a great deal.

Business Insider reported October 6 that 26.8% of active Tampa listings had a price drop in the four weeks ending September 20, citing Redfin. That figure describes asking-price reductions in the report’s Tampa market. It does not mean home values fell by that percentage.

That difference matters. A seller can reduce an ambitious asking price and still be above the range supported by comparable sales. Another seller might make a smaller adjustment that puts an already reasonable listing in a very competitive position. You have to look at the house and the numbers together.

Compare the new price with the right homes

Start with recent sales that buyers would reasonably compare to the property. Look at the neighborhood, size, age, condition, and major features. A pool, a different lot, or a newer roof can affect how useful a comparison really is.

Then look at what else you can buy today. If you are considering a home in Zephyrhills, I would want to know how it compares with similar resale listings and any new construction you would actually consider. Compare the full terms, too. A lower sticker price is only one part of the decision.

I would also review the listing history. When did the property first come on the market? Have there been several changes? Did it go pending and then return? Those questions can help us decide what to ask the listing agent. They do not establish that anything is wrong with the home.

Find out what you may need to spend after closing

A house can fit your purchase budget and still require more cash than you want to spend during the first year. Before getting too attached, think through the roof, air conditioning, appliances, and any visible maintenance issues.

Keep cosmetic preferences separate from repairs you may need to address soon. You can choose to live with an older kitchen. A significant problem identified during an inspection may require a different decision. Get qualified estimates when the possible cost could affect whether you proceed.

For my own comparison worksheet, I would put the purchase price beside estimated immediate repairs, expected community charges, and a realistic maintenance allowance. That makes it easier to compare an updated home with one that looks cheaper but needs work.

Decide what would make an offer work for you

Before negotiating, get clear about your priorities. Are you trying to reduce the monthly payment, preserve cash for moving, or avoid taking on a repair? That answer should help shape the conversation with your agent and lender.

Ask the lender to compare any proposed financing or closing-cost arrangements before you commit. The offer needs to work within the loan program and your available funds. It also needs to make sense to the seller. There is no universal discount that applies just because a listing has been reduced.

Keep your budget in charge of the decision

I would rather see you buy a home that works at a comfortable payment than stretch because the listing shows a large reduction from its original price. Decide what you can spend before the negotiation gets going, and keep enough money available for the move and the normal expenses of ownership.

A reduced listing may be an opportunity. The way to find out is to check comparable homes, understand the condition, and run your own numbers. If you have been watching a property with a recent price change, what would you need to know before going back to see it?

Posted in Buyer Tips